QUICK TAKE:
- Source: Written reply by MoS Commerce & Industry Jitin Prasada in Parliament, March 2026
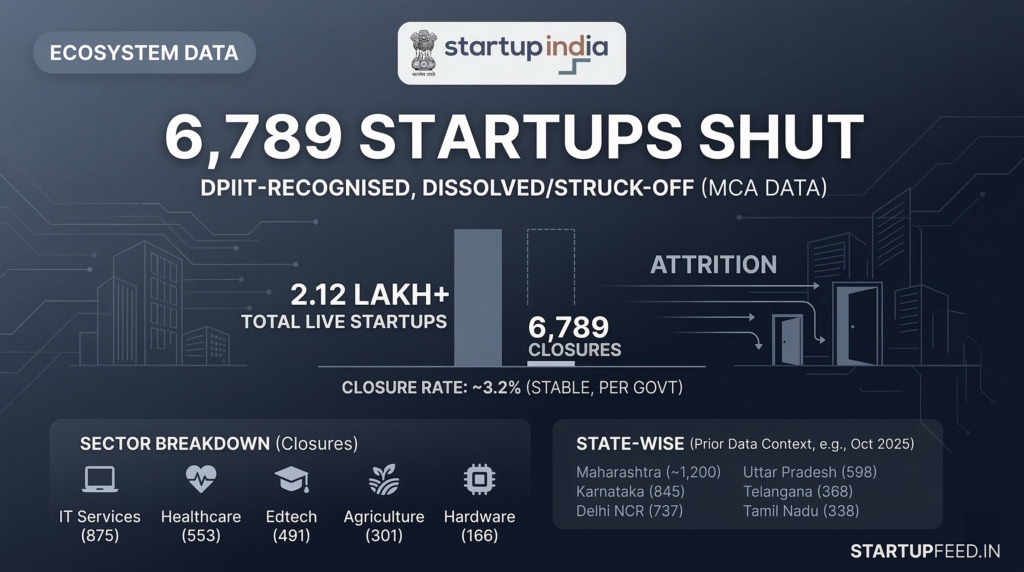
- Headline number: 6,789 DPIIT-recognised startups categorised as closed (dissolved/struck-off) by Ministry of Corporate Affairs — as of January 2026
- Total live ecosystem: 2.12 lakh DPIIT-recognised startups as of January 31, 2026 — up from 1.97 lakh (Oct 2025) and 2.07 lakh (Dec 2025)
- Closure rate: ~3.2% of all ever-recognised startups — remarkably stable vs 3.3% (Dec 2024), 3.2% (Oct 2025)
- Top sectors by closure: IT services (875) > Healthcare & lifesciences (553) > Edtech (491) > Agriculture (301) > Hardware (166)
- State-wise (prior data): Maharashtra leads closures, followed by Karnataka, Delhi, UP, Telangana and Tamil Nadu
- SISFS update: 219 incubators selected; Rs 945 Cr corpus committed under Startup India Seed Fund Scheme
- FFS update: Rs 10,000 Cr corpus; all committed to 144 AIFs under SIDBI; Rs 21,276 Cr+ invested in 1,173 startups
- Govt position: No increase in startup closures observed — closures attributed to business model viability, market alignment and macroeconomic conditions
For every 31 startups that India’s DPIIT has recognised since 2016, exactly one has shut down.
That is the ratio embedded in the data tabled by Minister of State for Commerce & Industry Jitin Prasada in Parliament in March 2026: 6,789 DPIIT-recognised startups have been categorised as closed (dissolved or struck off by the Ministry of Corporate Affairs) as of January 2026 — while India’s total DPIIT-recognised startup count crossed 2.12 lakh at the end of the same month.
The sectoral breakdown accompanying the data is the most detailed slice of India’s startup attrition picture that Parliament has seen in a public reply. IT services leads with 875 closures, followed by healthcare & lifesciences (553), edtech (491), agriculture (301), and hardware (166). Together these five sectors account for 2,386 closures — or 35.1% of total shutdowns, despite representing a fraction of the total sector count.
The government’s position — that it has not observed any increase in startup closures — is mathematically defensible: the closure rate has held steady at approximately 3.2–3.3% of all ever-recognised startups across the last three parliamentary data-points. But the absolute number of closures continues to rise simply because the denominator — the total recognised startup base — is growing at roughly 5,000–8,000 new recognitions per quarter.
The Closure Data: Progression Over Time
| Data Point (Parliament Reply) | Total DPIIT Recognised | Closures | Closure Rate |
|---|---|---|---|
| Dec 2024 (Lok Sabha) | ~1,52,000 | 5,063 | 3.33% |
| October 2025 (Lok Sabha, Dec 2 reply) | 1,97,692 | 6,385 | 3.23% |
| December 2025 (Rajya Sabha, Feb 14 reply) | 2,07,135 | ~6,500 (est.) | ~3.14% |
| January 2026 (Parliament reply, Mar 2026) | 2,12,000+ | 6,789 | ~3.20% |
Note: Closure rate = Closed / Total recognised startups since inception. Consistency across data points supports government’s ‘no increase’ claim. Absolute closure numbers rising due to expanding denominator.
Sector-Wise Closure Breakdown (January 2026)
| Sector | Closures | % of Total Closures | Closure Insight |
|---|---|---|---|
| IT Services | 875 | 12.9% | Largest sector overall; also highest absolute closures. IT services remains the biggest startup category by count — high absolute attrition is expected at scale. |
| Healthcare & Lifesciences | 553 | 8.1% | Long regulatory cycles, high capital burn, and reimbursement uncertainty create structural failure risk. Post-COVID funding tailwinds reversed sharply in 2023–24. |
| Edtech | 491 | 7.2% | Most structurally challenged sector post-2022. Byju’s collapse, GST on digital services, and the post-pandemic return-to-school effect decimated the consumer edtech segment. Edtech funding fell 46% YoY in 2024. |
| Agriculture | 301 | 4.4% | India’s 3rd-largest employer among startups by jobs, but high operational complexity, low margins, weather risk and last-mile distribution failures remain persistent closure drivers. |
| Hardware | 166 | 2.4% | Capital-intensive segment with high manufacturing and supply chain risk. Hardware startups face 3–5x longer go-to-market cycles vs software; most closure-prone per rupee of capital deployed. |
| All other sectors (50+) | 4,403 | 64.9% | Remaining closures spread across 50+ DPIIT-tracked industries including fintech, logistics, D2C, cleantech, AR/VR, gaming, robotics, and more. |
| Total | 6,789 | 100% |
State-Wise Closure Data (Based on October 2025 Parliamentary Reply)
Note: The March 2026 reply did not include a fresh state-wise breakdown. The state data below is from the October 2025 parliamentary reply (6,385 total closures), which is the most recent state-level data in the public domain. The distribution is expected to be similar for the January 2026 figure.
| State / UT | Closures (Oct 2025 Data) | Share of Total | Context |
|---|---|---|---|
| Maharashtra | ~1,200 | 18.8% | India’s largest startup state by recognition count; leads closures in absolute terms. Mumbai’s fintech, healthtech and D2C ecosystem has seen the sharpest post-funding-winter corrections. |
| Karnataka | 845 | 13.2% | Bengaluru’s large IT services and consumer internet base drives absolute attrition; proportional closure rate broadly in line with national average. |
| Delhi NCR | 737 | 11.5% | Third-largest hub; edtech (significant Delhi-based cohort from BYJU’s era), fintech, and B2B SaaS closures prominent. |
| Uttar Pradesh | 598 | 9.4% | Large absolute base driven by StartInUP programme and AKTU-affiliated incubation; many early-stage and first-generation startups with higher natural attrition. |
| Telangana | 368 | 5.8% | Hyderabad-based deep tech, pharma tech, and agri-tech closures; T-Hub’s large portfolio includes early-stage ventures with higher failure rates. |
| Tamil Nadu | 338 | 5.3% | Chennai’s manufacturing-adjacent hardware and medtech startups carry higher capital risk; many closures concentrated in hardware and health sectors. |
| All other states/UTs | 2,299 | 36.0% | Rest of India — Rajasthan, Gujarat, MP, Bihar, Punjab, and others contribute the remaining closures. |
StartupFeed Insight — Reading the Numbers Correctly
The government is technically accurate when it says there is ‘no increase in startup closures’ — the closure rate has held at 3.2–3.3% since at least 2024. But this framing obscures three more important structural observations:
- Edtech is the sector most disproportionately represented in closures.
Edtech’s 491 closures represent ~7.2% of total shutdowns. But edtech’s share of total DPIIT-recognised startups is significantly smaller than IT services, fintech, or healthcare. When measured against its share of the recognition base, edtech’s proportional closure rate is almost certainly the highest among major sectors — reflecting the structural collapse of the consumer edtech model post-2022 (Byju’s bankruptcy, NEET controversy fallout, return-to-classroom).
- Agriculture’s 301 closures are a demand-side signal, not just a supply-side failure.
The agritech sector is India’s third-largest startup employer but the structural mismatch between VC-backed go-to-market models and Indian farmers’ actual purchasing behaviour has driven persistent failure. Most agritech closures are input delivery, crop advisory, or marketplace startups that underestimated distribution costs and farmer wallet share. The surviving cohort is increasingly focusing on B2B (selling to agri-corporates, FPOs, and mandis) rather than D2F (direct-to-farmer).
- The DPIIT closure count is structurally undercounted — and the government knows it.
The 6,789 figure only tracks startups that are formally dissolved or struck off by the MCA — a legal process that can take 1–3 years after a startup actually stops operating. Many ‘zombie startups’ (DPIIT-recognised, MCA-active but operationally dead) are not captured in this count. Independent ecosystem estimates put actual startup failures at multiples of the official MCA closure figure. This is not a criticism of the data methodology — MCA records are the only objective, verifiable source — but it is an important context for interpreting the 3.2% closure rate as a floor, not a ceiling.
The real story: 2.12 lakh recognised + 22 lakh jobs is a milestone worth celebrating.
The net growth trajectory is unambiguously positive. India has added roughly 15,000 new DPIIT-recognised startups per quarter in recent quarters. The ecosystem crossed 2 lakh recognitions, created over 21.9 lakh direct jobs, and is seeing accelerating deep tech recognition under the February 2026 gazette notification. The closures are churn, not collapse — and 3.2% is a remarkably low formal dissolution rate for any high-risk, early-stage asset class.
Government’s Three Flagship Funding Schemes: Current Status
| Scheme | Corpus | Status (Jan 2026) | How It Works | Key Numbers |
|---|---|---|---|---|
| Fund of Funds for Startups (FFS) | Rs 10,000 Cr | Entire corpus committed to 144 SEBI-registered AIFs; SIDBI is operating agency; DPIIT is monitoring agency | FFS invests in AIFs, which invest in startups. Target: each AIF deploys 2x the FFS commitment in startups. | Rs 6,886 Cr committed by DPIIT to SIDBI; Rs 11,687 Cr committed by SIDBI to AIFs; Rs 21,276 Cr+ invested in 1,173 startups |
| Startup India Seed Fund Scheme (SISFS) | Rs 945 Cr | 219 incubators selected across India; operational since April 1, 2021 | Provides grants up to Rs 20 Lakh for proof-of-concept/prototype; up to Rs 50 Lakh as seed funding via DPIIT-approved incubators. | 219 incubators selected; Rs 945 Cr corpus committed; covers all stages from ideation to market entry |
| Credit Guarantee Scheme for Startups (CGSS) | Open-ended guarantee scheme | Implemented by NCGTC (National Credit Guarantee Trustee Company Limited) | Provides credit guarantees on loans to DPIIT-recognised startups from commercial banks, NBFCs, and venture debt funds. | 260 loans worth Rs 604.16 Cr guaranteed to 209 startups (as of Jan 2025); Rs 27.04 Cr to 17 women-led startups |
The DPIIT 2026 Policy Context: Recognition Framework Overhauled
This closure data sits alongside a major structural change in how DPIIT recognises startups. A new Gazette Notification (February 4, 2026) superseded the 2019 framework — with three critical changes for the ecosystem:
| Change | Old Framework (2019) | New Framework (Feb 4, 2026) | Implication |
|---|---|---|---|
| Recognition period — Deep Tech | 10 years from incorporation (same as all startups) | 20 years from incorporation — a full decade extension | Reduces ‘graduation cliff’ for deep tech ventures with 10+ year R&D cycles (biotech, space, semiconductors, defence). Directly addresses a chronic failure driver for deep tech startups. |
| Turnover ceiling | Rs 100 Cr (regular); Rs 100 Cr (deep tech) | Rs 200 Cr (regular); Rs 300 Cr (deep tech) | Prevents commercially scaling companies from losing DPIIT benefits (tax exemptions, AIF eligibility, GeM procurement access) prematurely. Raises the bar for what counts as ‘graduated’ from startup status. |
| Eligible entity types | Companies; LLPs only | Now includes Multi-State Cooperative Societies and State/UT Cooperative Societies | Opens DPIIT recognition to agri cooperatives, rural tech ventures, and community-owned enterprises — directly targeting the agritech segment that shows high closures. |
| Deep Tech definition | Not formally defined | Formally defined: entities with high R&D spend, novel IP ownership, and solutions based on scientific/engineering advancements | For the first time, the DPIIT 2026 notification creates a legally distinct category — enabling targeted policy, tax, and funding treatment for deep tech separate from services/consumer internet startups. |
India’s Startup Milestone Progression: From 502 to 2.12 Lakh
| Year | Recognised Startups | Net Addition | Key Context |
|---|---|---|---|
| 2016 (base year) | 502 | — | Startup India launched January 16, 2016; initial recognitions under new framework |
| 2022 | ~84,000 | ~83,500 over 6 years | COVID-era digital surge drives recognition volume; VC funding at peak ($22.4 Bn in 2022) |
| June 2024 | 1,40,803 | +56,803 in ~18 months | Consistent acceleration; 51% from Tier II/III cities |
| December 2024 | ~1,57,706 | +16,903 in 6 months | Funding winter deepens; 5,063 closures on record |
| October 2025 | 1,97,692 | +39,986 in 10 months | Fastest addition pace; 6,385 closures; 21.11 lakh jobs |
| December 2025 | 2,07,135 | +9,443 in 2 months | Crosses 2 lakh milestone; 2025 funding: $10.5 Bn (-17% YoY); 21.9 lakh jobs |
| January 2026 | 2,12,000+ | +~4,865 in 1 month | Current data point; 6,789 closures; 219 SISFS incubators; new recognition framework Feb 2026 |
| 2025 (full year) | 49,429 new recognitions | Highest single-year addition | Self-reported job creation: 4.67 lakh direct jobs added in 2025 alone |
What’s Next: Five Policy and Ecosystem Signals to Watch
Deep tech pipeline acceleration: The Feb 2026 gazette notification’s 20-year recognition window + Rs 300 Cr turnover ceiling for deep tech will trigger a fresh wave of deep tech DPIIT applications in 2026, particularly from biotech, space, semiconductor design, and defence robotics ventures.
Agritech restructuring: Agriculture’s 301 closures reflect the failure of the D2F (direct-to-farmer) model. Watch for surviving agritech startups to pivot toward B2B agri-input supply chains, FPO digitisation, and precision farming tools — segments with more defensible unit economics.
Edtech consolidation continues: Edtech’s 491 closures are likely still a lagging indicator of the 2022–23 correction. Expect further attrition in consumer edtech, but accelerating growth in B2B skilling, enterprise learning, and hybrid/offline models that escaped the post-Byju’s carnage.
SISFS expansion: With 219 incubators and Rs 945 Cr committed, SISFS is the government’s most direct early-stage intervention tool. Monitor disbursement velocity vs corpus commitment — the gap between committed and actually disbursed capital is the key metric for real-world impact.
MCA zombie startup count: The 6,789 formal closures are a floor. Parliament should be asked for data on ‘inactive-but-not-dissolved’ DPIIT-recognised startups — a figure that would reveal the true scale of the funding winter’s attrition. This is the question the current data does not answer.
StartupFeed tracks DPIIT policy developments, government scheme data, and ecosystem metrics. Follow @StartupFeed_in for real-time updates
Liked this story? Follow StartupFeed on Google so our reporting reaches you first.