Published: November 6, 2026
StartupFeed Quick Take
- The MobiKwik NBFC arm, MFSPL, received its RBI registration on November 5, 2026.
- Lending starts in three to six months, targeting Rs 5,000 crore in loans over three to four years.
- Q2 FY27 net profit set a record at Rs 11.8 crore, a fourth straight profitable quarter.
Gurugram fintech MobiKwik won its final RBI registration on November 5, 2026, clearing its arm MFSPL to lend directly for the first time.
MobiKwik plans to start lending within three to six months. It is targeting a loan book of Rs 5,000 crore within three to four years.
That goal sits on a better base. In the September quarter, MobiKwik turned a record net profit, a year after it was deep in the red.
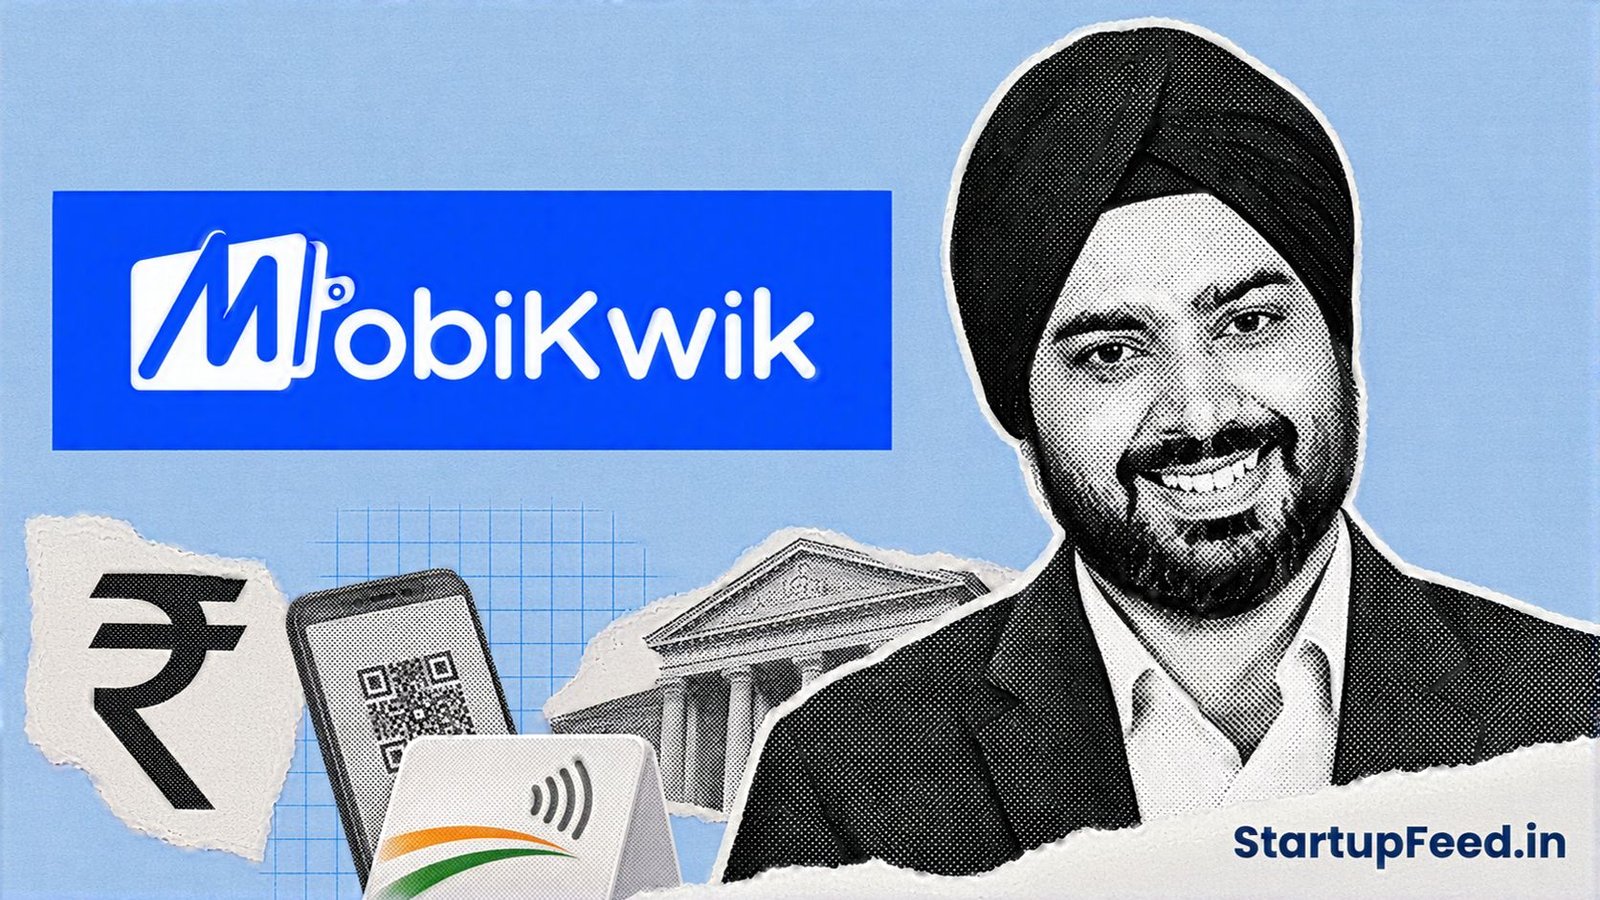
Bipin Preet Singh, who leads MobiKwik, set the ambition plainly:
“Doing (just) a 10-billion-rupee NBFC is not our ambition. Our goal is that at least in the next three to five years, we will have a book of 50 billion rupees.”
Bipin Preet Singh, co-founder and chief executive, MobiKwik. From an interview reported by DealStreetAsia, 2026.
The MobiKwik NBFC arm can now lend directly
An NBFC is a non-bank lender. The registration lets MobiKwik Financial Services Private Limited, called MFSPL, give out loans on its own.
Until now MobiKwik only helped other lenders find and manage borrowers. MFSPL is a wholly owned arm of MobiKwik.
The RBI gave its first-stage approval in April 2026, and MobiKwik put Rs 9.99 crore into the unit in October 2025.
The new licence will let MobiKwik build and price its own credit products. It can also keep working with its bank and NBFC partners, so the arm adds to the old model rather than replacing it.
MobiKwik will focus on secured and unsecured loans for consumers and small businesses. It serves over 186 million users and 4.79 million merchants, most of them in smaller cities.
How the Rs 5,000 crore co-lending plan works
MobiKwik will lend through a co-lending model with banks and other NBFCs. It plans to route about 10% of its digital loans through MFSPL at the start.
Here is what that means in rupees. If MobiKwik gives out Rs 6,000 crore in loans next year, about Rs 600 crore would flow through MFSPL.
Under a 10:90 split, MobiKwik funds a tenth of each loan and its partner funds the rest. So Rs 600 crore of loans would need about Rs 60 crore of MobiKwik’s own money.
This keeps the model light on capital. MobiKwik says it wants faster product launches while it keeps its lender partners.
Q2 profit set a record at Rs 11.8 crore
Its Q2 results show a net profit of Rs 11.8 crore in the September quarter, against a loss of Rs 28.6 crore a year earlier.
It was the highest quarterly profit in MobiKwik’s history and its fourth profit in a row. The loss a year ago included a one-time charge of Rs 11.8 crore for a merchant fraud.
Operating revenue rose 9.4% from a year ago to Rs 295.7 crore. The table below sets the main numbers side by side.
| Measure | Q2 FY27 | Q2 FY26 |
|---|---|---|
| Revenue from operations | Rs 295.7 Cr | Rs 270.2 Cr |
| Total income | Rs 302.8 Cr | Rs 279.3 Cr |
| Net profit / (loss) | Rs 11.8 Cr | (Rs 28.6 Cr) |
Profit also rose 55.4% from Rs 7.62 crore in the June quarter. For the first half of FY27, MobiKwik made Rs 19.45 crore, against a Rs 70.54 crore loss a year earlier.
Payments drove the quarter, with volumes up 35% from a year ago to Rs 59,677 crore. Revenue from financial services, including its ZIP EMI product, rose 41.8% to Rs 86.9 crore.
Loans given out through MobiKwik’s partners rose 34.1% from a year ago to Rs 1,082.6 crore. They also jumped 46.9% from Rs 736.7 crore in the June quarter.
The earlier dip came from a technology move while MobiKwik shifted its lending business. Its major lender partners grew to 11, from six a year ago.
Lending costs fell 16.4% to Rs 29.8 crore. MobiKwik shares closed 2.3% higher at Rs 224.75 on the BSE after the news.
What comes next for MobiKwik’s lending
MobiKwik expects strong double-digit growth in lending, though it warned the pace may slow. The licence took under four months to clear after the first-stage approval.
About 79% of its loans last quarter used a first-loss guarantee, where MobiKwik covers early defaults. The rest, about 21%, came through a pure distribution model, where MobiKwik only passes on loans.
Over time, direct lending through MFSPL should lift MobiKwik’s share of each loan’s economics. MobiKwik listed in December 2024 after a Rs 572 crore IPO, and its shares have been volatile since.
What this means for you: If you build a lending or co-lending startup, MobiKwik now moves from partner to direct rival in consumer and small-business credit. Watch the next two quarters for its first in-house loans and the capital it sets aside for the Rs 5,000 crore book.
StartupFeed Insight
The licence is less about new money and more about control. On a 10:90 split, roughly Rs 60 crore of MobiKwik’s own capital can support about Rs 600 crore in loans. So the Rs 5,000 crore target is reachable without heavy balance-sheet strain. The real test is credit quality once MobiKwik owns a slice of each loan, not just the fee. Watch its December 2026 quarter results for the first in-house lending figure and the provision it books against it. If profit holds through Q3 FY27 while the book grows, the model works. If provisions spike, the market will punish it fast.
By Avinash Mishra, Business Correspondent
Have a tip? Write to us at editorial@startupfeed.in.
Disclaimer: This article is for information only and is not investment advice. StartupFeed and its authors are not SEBI-registered investment advisors. Please speak to a SEBI-registered advisor before investing.
Liked this story? Follow StartupFeed on Google so our reporting reaches you first.