Published: 18 October 2026
StartupFeed Quick Take
- The Burma Burma IPO has a fresh issue of up to Rs 150 Cr and a 2.79 Cr share offer for sale
- Hunger Pangs will spend Rs 117.3 Cr on 27 new outlets, about Rs 4.3 Cr each
- FY26 revenue rose 46.56% to Rs 155.50 Cr, but net loss rose about 30 times to Rs 15.37 Cr
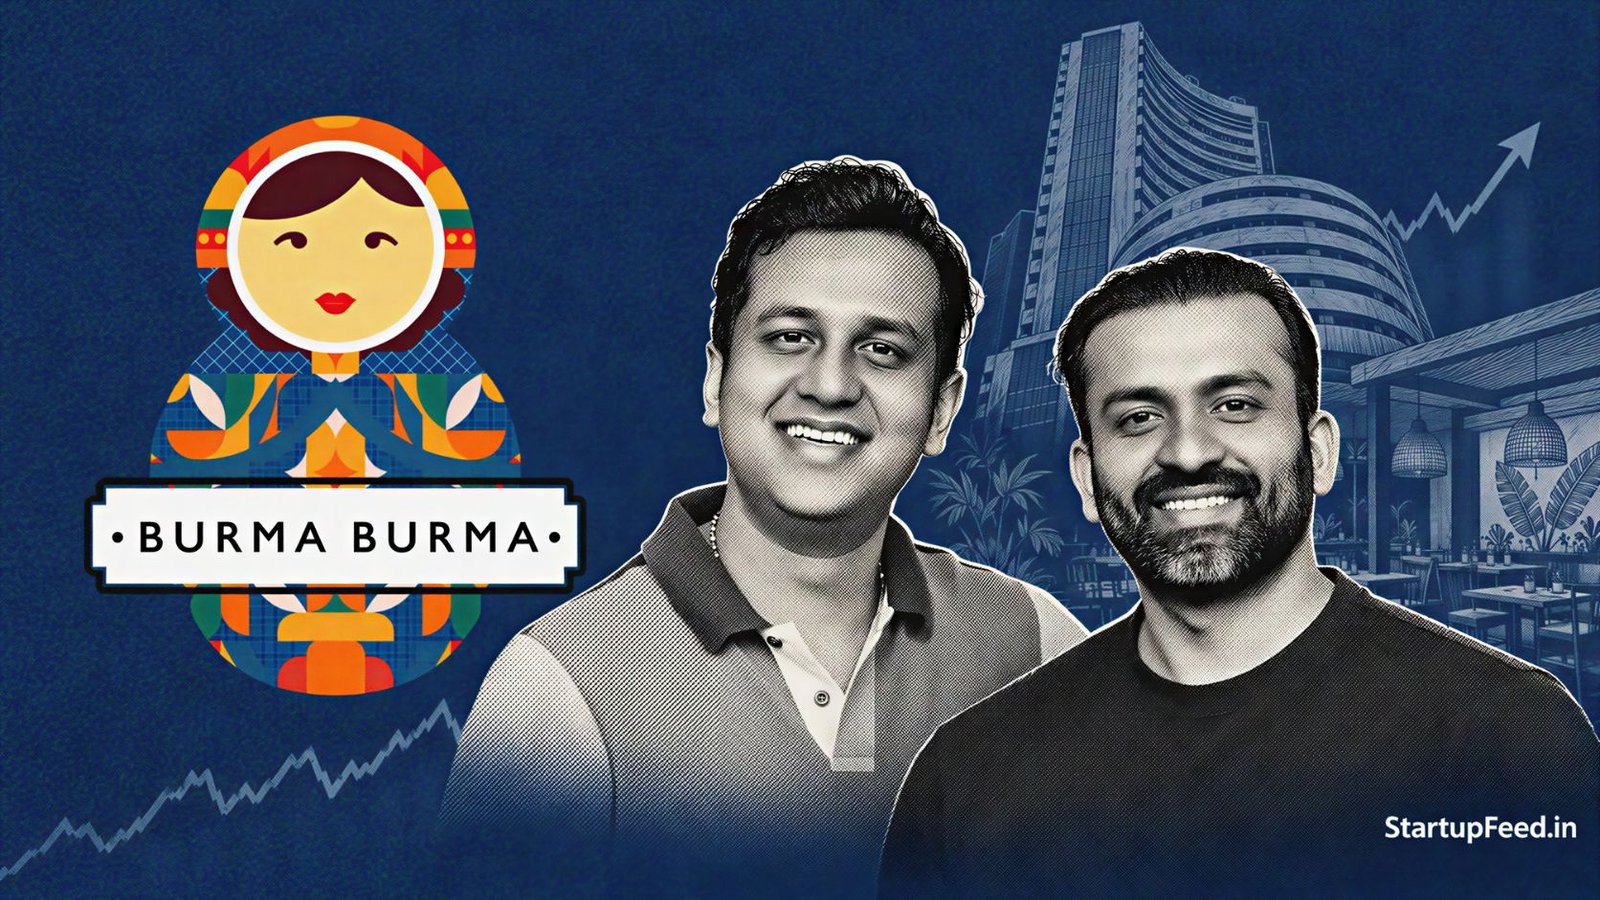
Mumbai-based Hunger Pangs, which runs the Burma Burma restaurant chain, filed its draft IPO papers with SEBI on October 16, 2026, seeking Rs 150 crore.
The draft red herring prospectus shows what that growth cost. Net loss for FY26 was Rs 15.37 crore. A year earlier: Rs 51 lakh.
Revenue grew 46.56% to Rs 155.50 crore. Reported EBITDA was Rs 25.68 crore. That leaves Rs 41.05 crore of costs sitting below the EBITDA line. EBITDA is profit before interest, tax and the cost of assets losing value over time.
Where the Burma Burma IPO money actually goes
Rs 117.3 crore of the Rs 150 crore fresh issue is set aside for 27 new Burma Burma outlets it will own and run. That is 78% of the money raised. It works out to about Rs 4.3 crore per outlet.
None of those 27 opens in FY27. Rs 10 crore goes out in FY27 on fit-outs and other preparation. Twelve outlets are due in FY28 and fifteen in FY29.
The rest of the fresh issue goes to general corporate purposes at Hunger Pangs. Burma Burma ran 22 outlets on July 31, 2026. Adding 27 more would take the chain past 49.
Ankit Gupta and Chirag Chhajer set up Hunger Pangs in 2013 and opened the first Burma Burma in Mumbai a year later. In January 2025, raising Rs 25.46 crore, Chhajer named the year he wanted to list:
“a key enabler in realizing our vision of being IPO-ready by 2027”
Chirag Chhajer, cofounder, Burma Burma. From the company’s funding announcement, January 2025.
The draft papers went in on October 16, 2026, about a year ahead of that target.
Revenue grew 47%, but the loss grew 30 times
Revenue from operations at Hunger Pangs rose by Rs 49.40 crore in FY26. Reported EBITDA rose by only Rs 4.33 crore. So the EBITDA margin fell from 20.12% to 16.51%, a drop of 3.6 percentage points.
| Figure | FY25 | FY26 |
|---|---|---|
| Revenue from operations | Rs 106.10 Cr | Rs 155.50 Cr |
| EBITDA | Rs 21.35 Cr | Rs 25.68 Cr |
| EBITDA margin | 20.12% | 16.51% |
| Net loss | Rs 0.51 Cr | Rs 15.37 Cr |
Rent, interest and the cost of assets losing value sit inside that Rs 41.05 crore gap. A chain opening outlets at speed carries all three. The 22nd outlet opened between June 30 and July 31 this year.
The average bill at a Burma Burma table was Rs 2,400 in FY26. Delivery brought in 10.76% of revenue from operations. Across the 1,991 seats the chain had on June 30, FY26 revenue is about Rs 7.8 lakh per seat.
Who is selling, and how much
The offer for sale is 2,79,29,760 shares. Ankit Gupta and Chirag Chhajer will sell up to 60 lakh shares each. Together that is 43% of the shares on offer.
Promoter group firm Bbigplas Poly is selling up to 42 lakh shares. Negen Tech Opportunities Angel Fund is selling up to 64.68 lakh, the largest single block.
Venture Catalysts Angel Growth Fund is selling up to 27.72 lakh shares. L V Angel Fund is selling up to 5.25 lakh.
Those six add up to 2,59,65,000 shares. The balance of about 19.6 lakh shares comes from three people: Nisarg Ajaykumar Vakharia, Shweta Sharma and Mehul Kirit Mehta. Money from the offer for sale goes to the sellers, not to Hunger Pangs.
In March 2026, a Rs 38 crore round valued Burma Burma at Rs 500 crore. Total funding before the IPO is about $11 million.
Only two of the five named sites are new cities
Hunger Pangs has signed letters of intent for five of the 27 planned sites. They are in Bengaluru, Surat, Jaipur, Kolkata and Delhi. Burma Burma’s own shareholder and locations pages list nine cities it already serves.
Those nine are Mumbai, Bengaluru, New Delhi, Gurugram, Noida, Chandigarh, Kolkata, Ahmedabad and Hyderabad. So three of the five named sites sit in cities Burma Burma is already in. Only Surat and Jaipur are new ground.
Jaipur would be the chain’s first address in Rajasthan. Surat would be its second city in Gujarat, after Ahmedabad.
Locations for the other 22 outlets are not fixed yet, and Hunger Pangs has not named them. A Japanese restaurant and noodle shop brand is also on the drawing board. That brand is still being worked on.
What this means for you: If you plan to apply to the Burma Burma IPO, the Rs 117.3 crore expansion plan builds nothing you can see in FY27. Wait for SEBI’s observations, due in one to three months, and read the restated accounts before the price band is set.
StartupFeed Insight
Hunger Pangs is a year early. Chirag Chhajer told investors in January 2025 that the aim was to be IPO-ready by 2027, and the draft papers went in during October 2026. That pull-forward matters more than the FY26 loss. EBITDA is up and the margin is down, which is what a chain opening outlets at speed looks like. The number to watch is the Rs 4.3 crore average cost per new outlet, and whether Surat and Jaipur earn like Mumbai. Expect SEBI’s observations by late January 2027, and no IPO-funded outlet revenue before FY28.
By Avinash Mishra, Business Correspondent
Disclaimer: This article is for information only and is not investment advice. StartupFeed and its authors are not SEBI-registered investment advisors. Please speak to a SEBI-registered advisor before investing.
Have a tip? Write to us at editorial@startupfeed.in.
Liked this story? Follow StartupFeed on Google so our reporting reaches you first.